
Business
Copper Holds Losses Below $14,000 on US Midterm Risks to Stocks
By Katherine Langford
Advertisement · Why this ad?
Katherine oversees editorial operations across all six brands. Before joining The Meridan Group, she spent 14 years at the Minneapolis Star Tribune, where she led the metro desk through its digital transformation. She holds a Master's in Journalism from Northwestern's Medill School.
More from Katherine →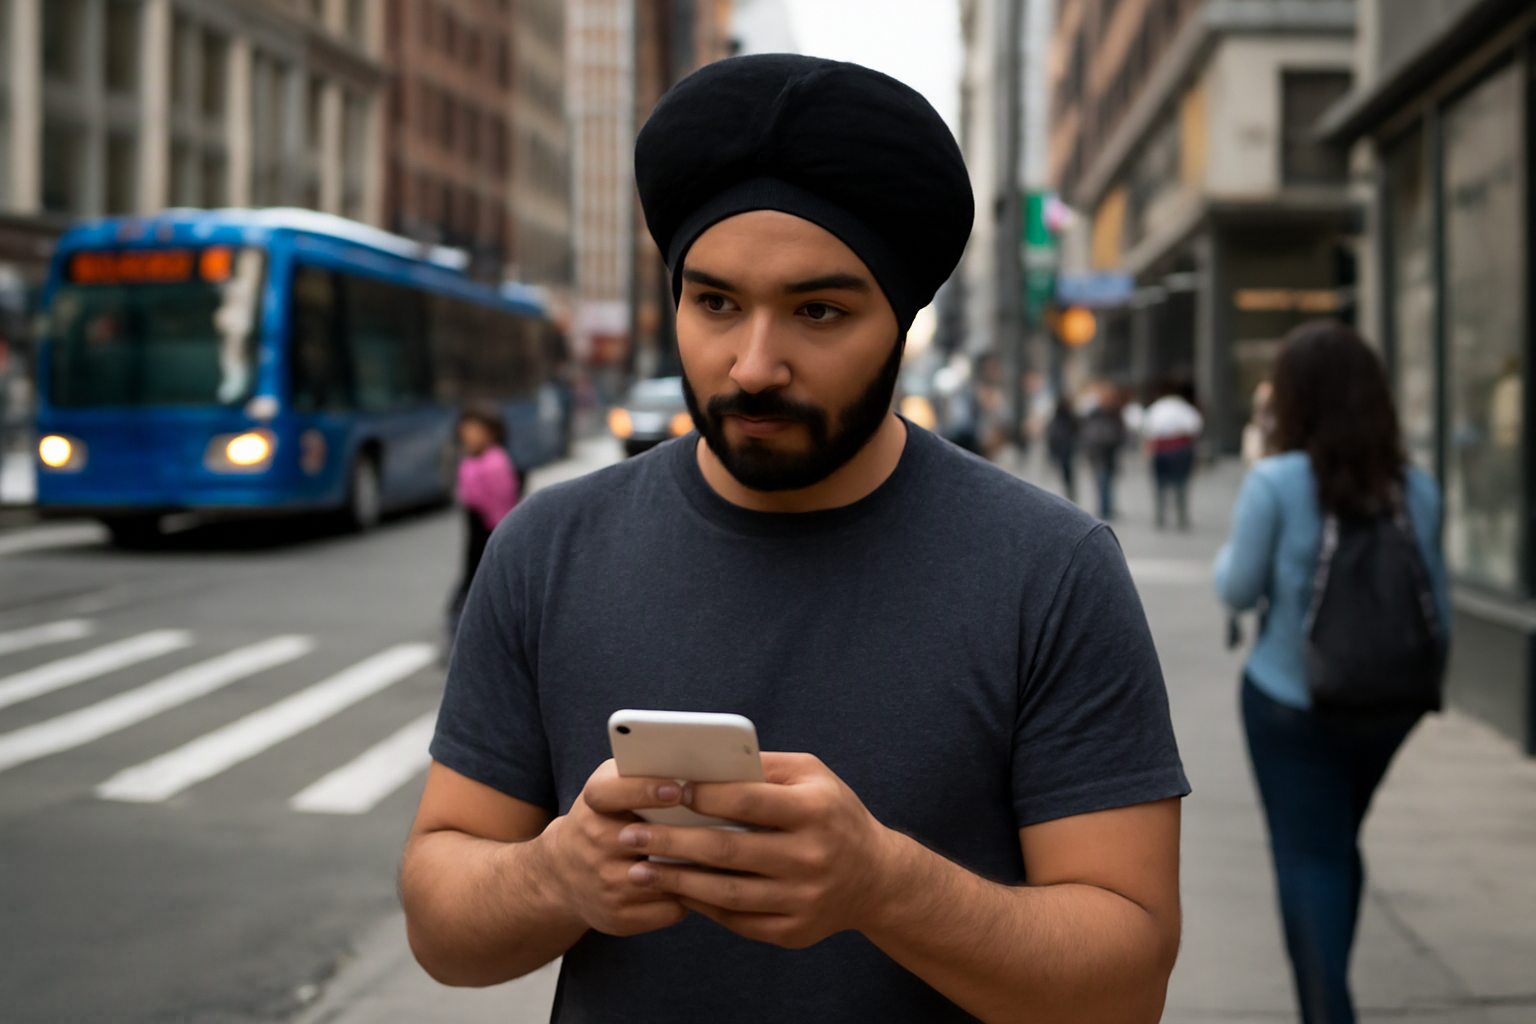
In the bustling streets of New Delhi, 25-year-old Navjot Singh stands as a testament to the aspirations of India’s burgeoning middle class. As a restaurant worker earning 50,000 Indian rupees (approximately $521) a month, Navjot faced a familiar dilemma: how to afford the luxuries that symbolize success and modern living. With an iPhone on his wish list, he turned to a small loan, marking the beginning of a spending spree that would include a PlayStation, a new television, and even a wine and spirits course. His choices reflect a broader trend among India’s middle class, where increasing disposable income is often accompanied by a rising debt burden.
India’s middle class has seen a remarkable transformation over the past decade. As economic growth has surged, so too has consumer spending. The country’s middle class is projected to reach 600 million by 2030, according to the World Bank. This demographic shift is not merely quantitative; it also embodies a qualitative change in lifestyle, with many seeking to indulge in products and experiences previously deemed unattainable.
However, this newfound prosperity has a flip side. Loans, credit cards, and other forms of debt have become increasingly accessible, enabling consumers like Navjot to finance their desires. While this has fueled economic growth, it has also led to a worrying trend: rising household debt levels. According to the Reserve Bank of India, household debt as a percentage of GDP has climbed steadily, raising alarms about sustainability and financial stability.
The allure of consumer goods is potent, particularly in a society that equates material possessions with success. For many in India, taking out loans is not just a financial decision; it is a cultural one. The desire to own the latest smartphone or gaming console is often seen as a rite of passage, a way to signal one’s status among peers.
Navjot’s experience is not isolated. Reports indicate that the average loan taken by Indian consumers has increased, with many opting for personal loans that come with high-interest rates. The Ministry of Corporate Affairs notes that unsecured loans are particularly popular among younger consumers, who are more willing to embrace debt as a means to achieve their aspirations.
This shift in consumer behavior is indicative of broader cultural changes within Indian society. As traditional values emphasizing frugality and saving give way to a more consumer-driven ethos, the implications for family structures and community dynamics are profound. The rise of social media has amplified this trend, with platforms showcasing lifestyles that many aspire to replicate.
For families, the decision to take on debt can strain relationships. High divorce rates, often attributed to financial stress, reflect the challenges many couples face in managing their finances. The importance of maintaining strong, intact families remains paramount, yet the pressures of modern consumerism can complicate this goal.
The impact of rising consumer debt is felt not only at the individual level but also within communities. As people spend more, local businesses benefit, leading to job creation and economic growth. However, this growth comes with a caveat: communities must grapple with the consequences of increased financial insecurity.
In New Delhi, where Navjot resides, the vibrancy of local markets is evident. Yet, as household debt rises, so too does the risk of default. Many families find themselves trapped in cycles of borrowing, struggling to meet monthly payments while trying to maintain their lifestyle. The National Bank for Agriculture and Rural Development has highlighted the importance of financial literacy programs to help consumers understand the implications of their borrowing.
Local leaders in New Delhi are increasingly aware of these issues. Community forums and workshops are being organized to discuss the impact of consumer debt on families and the community. These gatherings serve as platforms for sharing experiences, where individuals like Navjot can voice their concerns and learn from one another. Local NGOs are stepping in to provide guidance on managing finances, emphasizing the importance of budgeting and saving.
One such initiative is the “Debt Awareness Campaign” led by the Delhi-based NGO, Empower India. This organization focuses on educating young professionals about the dangers of excessive borrowing and promotes healthy financial habits. The campaign has attracted hundreds of participants, and feedback indicates that many attendees leave with a renewed sense of responsibility towards their finances.
Fortunately, initiatives are emerging to address these challenges. Organizations are working diligently to promote financial literacy among consumers, especially the younger generation. Programs aimed at educating individuals about budgeting, saving, and responsible borrowing are gaining traction.
For instance, the Financial Literacy and Consumer Protection initiative provides resources that empower consumers to make informed decisions. As more individuals become aware of the potential pitfalls of debt, the hope is that they will adopt more sustainable financial practices.
Moreover, local banks are beginning to offer workshops tailored to young professionals like Navjot, focusing on how to navigate the complexities of loans and credit. These workshops often feature guest speakers who have successfully managed their debts, providing relatable examples that resonate with attendees. The feedback from these sessions has been overwhelmingly positive, with many participants expressing relief at having a clearer understanding of their financial options.
Looking ahead, the trajectory of India’s middle class will be shaped by how effectively consumers manage their debt. Policymakers and financial institutions must collaborate to create an environment that fosters responsible borrowing while still encouraging economic growth. This balance is crucial for ensuring that the dreams of millions do not become burdens.
Navjot Singh’s story is emblematic of a larger narrative unfolding across India. As the middle class continues to expand and evolve, the challenge will be to maintain the delicate balance between aspiration and financial prudence. The future of India’s economy may depend on it, as families navigate the complexities of modern consumerism while striving to preserve the values that bind them together.
As the government considers regulations to curb predatory lending practices, the role of consumer advocacy groups will also become increasingly important. These organizations can provide the necessary checks and balances, ensuring that consumers are not taken advantage of in their quest for financial stability. The ongoing dialogue around consumer rights and protections will be critical in shaping a sustainable economic future for the middle class.
In addition, the government is exploring the implementation of a national financial literacy curriculum in schools, aiming to equip future generations with the tools they need to navigate the financial landscape. This initiative has garnered support from various stakeholders, including educators, parents, and financial experts who recognize the importance of early education in fostering sound financial habits.
As India’s middle class continues to grow, the lessons learned from current trends in consumer debt will serve as a crucial guide for both individuals and policymakers. The hope is that with increased awareness and proactive measures, the dreams of many will not only be pursued but also achieved sustainably, allowing the middle class to thrive without falling into the traps of excessive debt.
By Katherine Langford
By Marcus Chen
By Katherine Langford
By Marcus Chen